

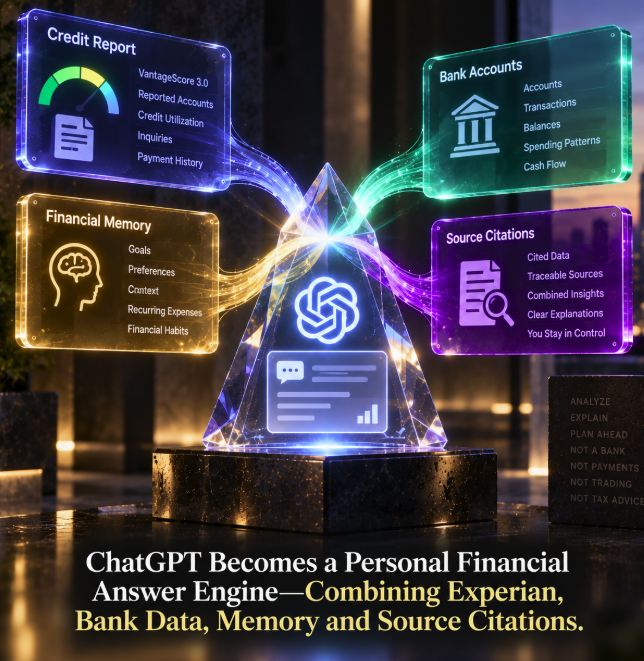

ChatGPT’s personal-finance product is moving beyond connected bank accounts into a broader financial-context layer. OpenAI is rolling out Experian credit-report connectivity for eligible U.S. Plus and Pro users, allowing ChatGPT Finances to reason over credit-report information alongside Plaid-connected accounts and the financial memories users have chosen to give ChatGPT.
The expansion turns Finances into something closer to a personal financial answer engine than a conventional budgeting dashboard. A user can ask questions about their financial situation and receive an explanation grounded in multiple forms of personal data, while ChatGPT can cite the financial source data it used so the user can inspect where an answer came from.
The underlying product was introduced earlier in 2026 and is documented in OpenAI’s Finances in ChatGPT documentation. Finances is available in the United States to eligible Plus and Pro users on web, iOS and Android, with gradual rollout meaning some eligible accounts may receive features later than others.
Experian adds the credit-report layer
The newly documented Experian connection extends the financial picture beyond transactions, balances and investments. Eligible users can connect their Experian report and bring credit information into the same ChatGPT environment where they already reason about spending, bills, savings, debt and net worth.
The connected credit context can include a VantageScore 3.0, reported accounts, credit utilization, inquiries and payment history. Experian describes VantageScore 3.0 as a credit-risk scoring model built from credit-report information; the score shown through the ChatGPT integration should therefore be understood as that model rather than assumed to be the same score a particular lender will use in an underwriting decision.
That distinction matters because consumers can encounter different scoring models in different contexts. ChatGPT can explain the connected information, but a displayed score is not a guarantee of how a lender will evaluate an application.
The credit data refreshes on a monthly cycle
The Experian connection is designed as continuing financial context rather than a one-time uploaded report. The connected data refreshes monthly, and users can receive notifications when important changes are detected.
That makes credit information part of an ongoing monitoring workflow. Instead of manually downloading a report and asking ChatGPT to interpret a static file, an eligible user can maintain a connection and return with questions as the available data changes.
The monthly cadence also means the experience should not be treated as a real-time underwriting feed. Users should pay attention to the date of the available information when investigating a very recent payment, balance change, inquiry or account update.
ChatGPT can combine credit and cash-flow context
The more significant architectural change is what happens when Experian data is considered alongside Plaid-connected accounts. Plaid gives ChatGPT access, with the user’s authorization, to supported financial-account information such as balances and transaction activity. Experian contributes a different view: the credit-report record.
Those datasets answer different questions. A bank connection can show what money is moving through accounts and where spending is occurring. A credit report can show reported obligations, utilization, inquiries and payment history. Combining them gives ChatGPT more context for explaining why two parts of a user’s financial picture may tell different stories.
OpenAI says users choose which accounts to connect and which data to share. The system can only reason over information that the relevant institution or provider makes available through those authorized connections.
Financial memories add context that institutions may not know
ChatGPT Finances also has a dedicated memory layer. OpenAI’s documentation says users can tell ChatGPT about information such as a savings goal, a private obligation, a planned purchase or a preferred minimum checking balance, and ChatGPT can save useful details as financial memories.
This creates a third kind of financial context. Experian supplies credit-report data, Plaid-connected institutions supply account data, and financial memories can represent facts or goals that may not appear in either external system.
A user might, for example, have money earmarked for a major purchase even though the bank account itself does not label those funds that way. A financial memory can give ChatGPT that missing intention when it explains cash flow or discusses tradeoffs.
The answer can cite the financial data behind it
OpenAI already documents that when ChatGPT uses connected financial data, it may cite the relevant source data so the user can review where the answer came from. The Experian expansion makes that provenance layer increasingly important because a single answer can draw from multiple financial systems.
A useful financial explanation should not merely produce a number. The user needs to know whether the claim came from a connected account, credit-report information or remembered context supplied directly to ChatGPT.
This is a significant difference from a generic financial chatbot. The goal is not only to answer a personal question but to ground the explanation in the user’s authorized financial context and make supporting data inspectable.
ChatGPT is becoming a retrieval layer across a person’s financial life
Viewed architecturally, Finances is developing the same retrieval pattern appearing elsewhere in ChatGPT: multiple authorized data sources become context that the model can use when answering a question.
The difference is that financial retrieval is unusually sensitive and structured. Transaction records, balances, investment positions, credit utilization and payment history are not simply background personalization signals. They can materially change the meaning of a financial question.
That makes source visibility especially valuable. If ChatGPT says a user’s revolving utilization increased, the user should be able to inspect the underlying financial source rather than treating the model’s sentence as an independent financial record.
ChatGPT can explain, but it cannot execute the financial action
OpenAI maintains a strong boundary between analysis and execution. Its Finances documentation says ChatGPT can help users understand, plan and evaluate financial decisions, but it cannot move money, pay bills, change account settings, make trades, change retirement contributions, open or close financial accounts or file taxes.
The Experian connection does not turn ChatGPT into a credit-repair service capable of submitting disputes on the user’s behalf. It can help interpret connected credit information and explain possible next steps, but actions involving a credit bureau, lender or financial institution remain outside the assistant’s execution boundary.
OpenAI also states that ChatGPT is not a fiduciary, registered investment adviser, broker-dealer, tax preparer or law firm. Financial responses are intended for information and planning rather than as a replacement for professional advice where that is required.
This is not the same as ChatGPT for Financial Services
OpenAI now has two products whose names can easily be confused. Personal Finances in ChatGPT is the consumer experience for eligible U.S. Plus and Pro users connecting their own financial context. ChatGPT for Financial Services is a separate enterprise-oriented offering for financial institutions, focused initially on investment banking and equity research with professional datasets and organizational controls.
The Experian integration belongs to the personal-finance story: helping an individual understand their own financial picture. It should not be confused with the institutional research product.
Credit reports create a more consequential accuracy problem
Financial dashboards already require users to account for delayed syncs, incomplete institution data and transaction categorization errors. Credit-report interpretation raises the stakes because users may make important decisions based on what they see.
OpenAI’s general Finances guidance repeatedly tells users to inspect the underlying data when something looks wrong. That principle becomes even more important with credit information. ChatGPT can explain what the connected report says, but the authoritative record remains the underlying provider data, and users should verify unexpected entries directly with the relevant source.
The model can also make mistakes. Source citations help reduce that risk by giving users a path back to the financial evidence instead of asking them to trust an unsupported generated conclusion.
Monthly refreshes turn financial Q&A into an ongoing relationship
A static personal-finance chatbot starts over every time the user asks a question. ChatGPT Finances is moving in the opposite direction. Connected accounts update, credit information refreshes, and financial memories preserve user-supplied context across conversations.
That allows questions to become longitudinal. A user can ask what changed, why a financial metric moved, whether a spending pattern is improving or how a new credit-report event fits into broader goals.
The value increasingly comes from continuity rather than any single answer.
Financial memory is separate from the raw connected data
OpenAI describes financial memories as a dedicated form of memory used specifically to inform financial conversations. Users can review or delete those memories from the Finances experience.
Connected account data has its own lifecycle. OpenAI says users can disconnect accounts, and synced account data is scheduled for deletion from OpenAI’s systems within 30 days after disconnection. Information already written into conversation history is handled separately, so disconnecting a provider does not automatically erase previous chats that discussed the data.
This separation matters because “financial context” is not one database. It consists of provider connections, remembered user context and conversation history with different controls and retention behavior.
Temporary Chat creates another privacy boundary
OpenAI says Temporary Chats do not access connected financial accounts and do not use or create memories for personalization. That creates a useful distinction for users who want to discuss a general financial concept without bringing their connected personal-finance context into the conversation.
It also reinforces the broader product design: connected financial data is an optional context layer rather than something every ChatGPT conversation automatically receives.
Users deciding how to work with sensitive financial information should therefore pay attention not only to which providers are connected, but also to which ChatGPT mode they are using.
Experian makes the financial answer engine more complete
Before credit-report connectivity, ChatGPT Finances could already reason about spending, bills, subscriptions, net worth, investments and user-supplied financial goals. Experian adds another side of the household balance sheet: how credit obligations and payment behavior are being reported.
That creates questions that are difficult to answer from bank transactions alone. A cash-flow view can show that a payment left an account, while credit-report context can show how reported balances and payment history are represented in the credit system. Financial memories can then add the user’s own goal or constraint.
The result is a richer explanation layer, provided the user remembers that each source has its own update schedule, coverage and limitations.
Source citations may become the defining interface for personal AI finance
The more personal datasets an AI system can combine, the more important provenance becomes. A financial answer without visible grounding can be difficult to audit because the user may not know whether ChatGPT inferred something, remembered it or retrieved it from a provider.
OpenAI’s decision to expose citations to relevant connected financial data points toward a more inspectable model. The assistant can synthesize across sources, but the underlying evidence remains available for review.
This is especially important as AI products move from generic knowledge toward answering questions about an individual’s actual life. Personalization increases usefulness, but it also increases the cost of getting context wrong.
ChatGPT Finances is becoming a personal financial context engine
The Experian rollout pushes ChatGPT Finances beyond transaction analysis. For eligible U.S. Plus and Pro users, the system can bring credit-report information into an environment that already supports Plaid-connected financial accounts, financial memories and source-grounded answers.
ChatGPT remains an analytical layer rather than a financial execution system. It can explain, compare, summarize and help users reason about tradeoffs, but it cannot make payments, execute trades or carry out credit disputes for them.
The larger change is architectural: ChatGPT can increasingly answer a financial question using several different versions of the user’s financial reality at once. Experian can describe reported credit behavior, connected accounts can describe cash flow and balances, memories can describe personal goals, and citations can show which data informed the answer. That combination makes ChatGPT less like a generic finance chatbot and more like a personalized financial answer engine.